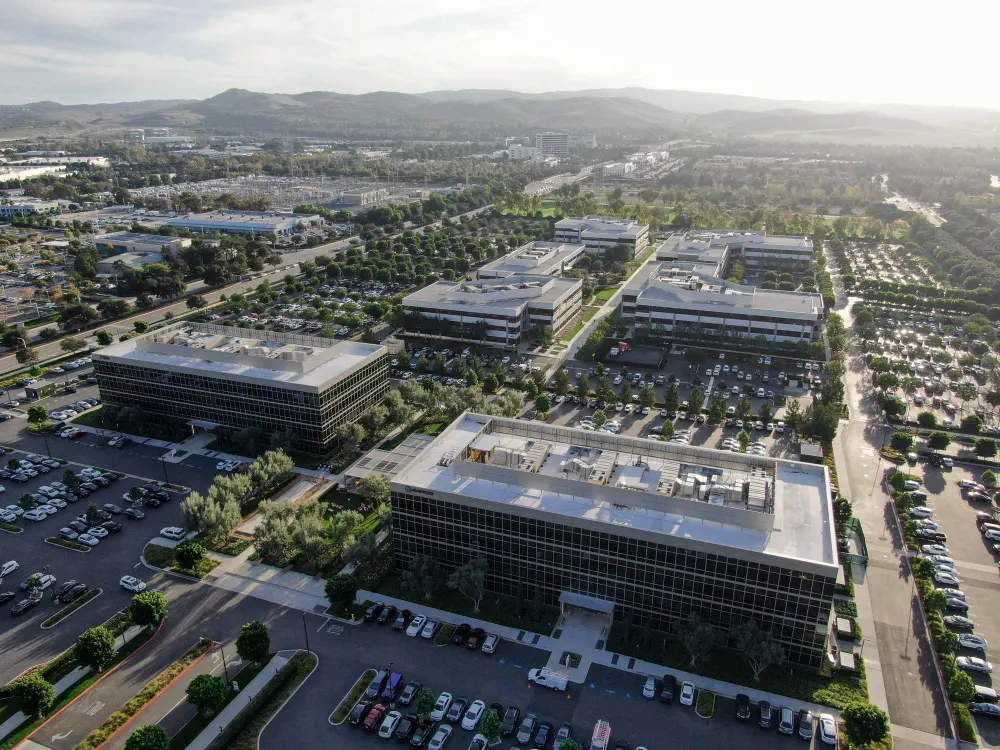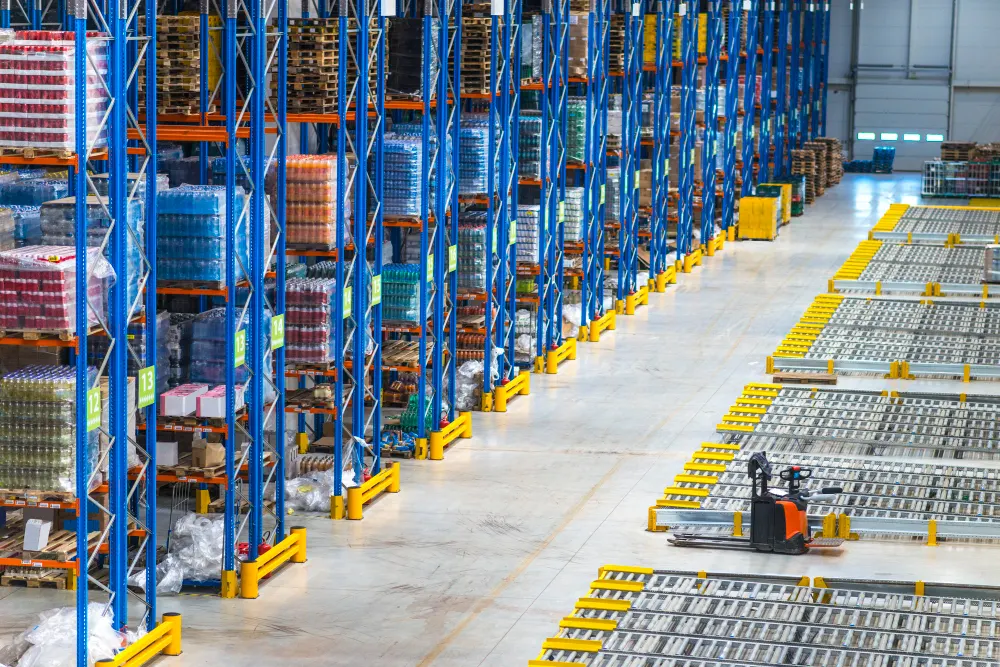
Purchasing commercial real estate represents one of the most significant financial decisions an investor can make, yet the difference between a profitable acquisition and a costly misstep often comes down to the quality of the property evaluation process. Unlike residential transactions, where comparable sales and emotional appeal frequently drive pricing, commercial real estate demands rigorous, numbers-driven analysis that examines every aspect of a property’s income potential, physical condition, legal standing, and market position. Whether you’re considering an industrial warehouse in Victorville, a retail center in Apple Valley, or an office building in San Bernardino, understanding the comprehensive evaluation framework that experienced commercial professionals employ will protect your capital and position you for sustained investment success.
The evaluation process begins long before you ever set foot on a property. Market analysis forms the critical foundation upon which all subsequent decisions rest, requiring investors to look beyond current conditions and project future supply and demand dynamics. In the Inland Empire’s diverse commercial landscape, this means analyzing employment growth trends, population migration patterns, infrastructure development timelines, and competitive property pipelines. A retail property might appear attractive based on current rent rolls, but if three competing shopping centers are planned within a two-mile radius, future vacancy risk could severely impact returns. Similarly, an industrial building might seem fairly priced today, but planned freeway improvements or rail expansions could either enhance or diminish its logistical value depending on specific access changes.
Physical property inspection represents the next critical evaluation phase, and commercial assets demand far more scrutiny than typical residential walkthroughs. Building systems—including HVAC, roofing, electrical, plumbing, and fire suppression—must be assessed not merely for current functionality but for remaining useful life and replacement costs. A roof with five years of remaining life might not require immediate expenditure, but capital planning must account for the $150,000–$400,000 replacement cost that will inevitably arise. Structural elements, foundation integrity, and seismic resilience take on heightened importance in California, where geological risks are ever-present. Engaging qualified structural engineers and building inspectors with specific commercial property experience is not an area where investors should seek cost savings.
Environmental assessment stands as arguably the most important—and potentially deal-breaking—component of commercial property evaluation. Phase I Environmental Site Assessments examine historical property uses, regulatory databases, and visual inspections to identify potential contamination risks. If recognized environmental conditions are identified, Phase II testing involving soil and groundwater sampling becomes necessary. In older industrial areas of San Bernardino or former agricultural zones in Newberry Springs, historical uses including manufacturing, fueling stations, or pesticide application can create liability exposure that survives property transfer. The Comprehensive Environmental Response, Compensation, and Liability Act (CERCLA) can impose cleanup costs on current property owners regardless of whether they caused the contamination, making thorough environmental due diligence not merely prudent but essential for financial protection.
Financial analysis moves beyond the simple purchase price to examine the complete investment proposition through multiple analytical lenses. Current Net Operating Income (NOI) provides the starting point, calculated by subtracting all operating expenses from gross rental income. However, sophisticated investors must stress-test this NOI against multiple scenarios. What happens if the largest tenant, comprising 40% of rental income, vacates upon lease expiration? How would operating expenses change if property tax reassessment follows acquisition? What capital improvements will be required over a five-year hold period, and how do these expenditures impact internal rate of return? Cap rate analysis provides a snapshot of current yield, but cash-on-cash return, equity multiple, and IRR offer more comprehensive pictures of investment performance over time.
Lease structure analysis reveals the true stability—or fragility—of a commercial property’s income stream. Triple-net leases, common in retail and some industrial properties, transfer operating expense responsibilities to tenants, creating more predictable cash flows for landlords. Full-service gross leases, more typical in office buildings, require landlords to manage and budget for operating expenses, introducing greater variability. Critical lease provisions including renewal options, escalation clauses, tenant improvement allowances, co-tenancy requirements, and use restrictions must be carefully reviewed. A retail lease with a national anchor tenant might seem secure, but if that lease contains a continuous operation clause or co-tenancy provision that allows termination if occupancy falls below a threshold, the investment risk profile changes dramatically.
Tenant credit analysis extends beyond current payment history to examine the financial strength and business viability of each occupant. A property fully leased to investment-grade credit tenants commands premium pricing because of the income security they provide. Conversely, a property leased to local businesses without audited financials or established operating histories carries greater default risk that should be reflected in the acquisition price. Understanding each tenant’s industry dynamics, competitive position, and lease expiration timeline allows investors to assess rollover risk and plan for potential re-leasing scenarios.
Legal and title review ensures that the property can be transferred free of encumbrances that would impair value or utility. Title reports reveal existing liens, easements, deed restrictions, and boundary issues that may not be apparent from physical inspection. Survey updates confirm that all improvements lie within property boundaries and comply with setback requirements. Zoning verification ensures that current and intended uses are permitted, while examination of any variances, conditional use permits, or planned development agreements reveals regulatory constraints or opportunities. In California’s complex regulatory environment, understanding the interplay between local, state, and federal requirements is essential for avoiding costly compliance surprises after acquisition.
Financing structure evaluation represents the final piece of the pre-acquisition puzzle. Commercial loan terms—including amortization schedules, prepayment penalties, recourse provisions, and reserve requirements—significantly impact investment returns and risk exposure. Interest rate risk must be carefully managed, particularly in volatile rate environments where floating-rate debt can quickly erode cash flows. Understanding lender requirements for tenant estoppels, SNDA agreements, and reserve accounts ensures smooth closing processes and avoids last-minute financing complications that can jeopardize transactions or force unfavorable terms.
The commercial property evaluation process is undeniably complex, requiring coordination between brokers, attorneys, accountants, engineers, environmental consultants, and lenders. Attempting to shortcut this process or rely on superficial analysis invites the kind of expensive surprises that destroy investment returns and consume management bandwidth. For investors in the Inland Empire’s dynamic commercial markets, engaging an experienced commercial real estate advisor who understands local submarket nuances, maintains relationships with qualified due diligence professionals, and can interpret evaluation findings within the context of specific investment objectives provides invaluable protection. The cost of comprehensive professional guidance is invariably modest compared to the expense of discovering hidden property deficiencies after closing. In commercial real estate, thorough evaluation isn’t just best practice—it’s the fundamental discipline that separates successful investors from those who learn expensive lessons.